How Often Should You Meet With Your Accountant? The Right Rhythm for a Growing Business
The biggest decisions in your business rarely happen neatly at year-end.
They happen while the business is moving: when you’re considering another hire, reviewing your prices, investing in equipment, or deciding whether you can afford the next stage of growth.
Yet many business owners have their most meaningful conversation with their accountant about a financial year that’s already ended. The figures may be accurate and every deadline may have been met, but there’s very little in those numbers that can still be changed.
So, how often should you meet with your accountant?
For a growing business, we recommend having up-to-date financial information every month, a meaningful review with your accountant at least quarterly, and additional conversations before significant decisions. Your year-end accounts remain essential, but they should form one part of a year-round accounting relationship.
The exact frequency will depend on your business. What matters is receiving the right information and support while there’s still time to use it.
How Often Should You Meet With Your Accountant?
There’s no single meeting schedule that will suit every business.
A relatively stable company with straightforward finances may not need a full meeting every month. A business growing quickly, managing tight cash flow, or preparing for a major investment may benefit from much more frequent support.
It’s also helpful to separate the frequency of your financial information from the frequency of your meetings. You may need current performance reports every month without needing an hour-long conversation every time one is produced.
For many growing businesses, a useful accounting rhythm looks like this:
| Fequency | Purpose | What It Should Help You Understand |
|---|---|---|
| Monthly | Visibility | What is happening in the business now? |
| Quarterly | Interpretation and decisions | Why is it happening, and what should we do next? |
| Annually | Compliance and longer-term review | What needs to be completed, and what have we learned? |
| When Needed | Decision support | What could this particular decision mean financially? |
Together, these different layers help you keep a finger on the pulse of the business, step back to understand the wider picture, and meet your statutory responsibilities.
Why Year-end Accounts Aren’t Enough to Run a Growing Business
Year-end accounts have an important job. Because they cover a financial year that has already ended, however, their primary purpose is to record and report on the past.
Imagine your profit margin began falling in the first quarter of the year. If that change only becomes visible when your annual accounts are prepared, several more months may have passed before you can investigate the cause.
The issue might be higher supplier costs, underpriced work, an unprofitable service, or a change in the way the team is spending its time. All of those things can be addressed, but the earlier you see them, the more options you have.
That doesn’t make year-end accounts any less important. The essentials need to be handled accurately and on time. But a growing business also needs financial information designed to help its owners run the business throughout the year.
What Should Monthly Accounting Support Show You?
Monthly financial information gives you a current view of business performance.
You might have heard this described as management accounts. At Ashton McGill, we call it performance reporting, because its purpose is to help you understand and improve the performance of the business.
A useful monthly report should help you see:
How revenue, profit, and margins are changing
What’s happening to cash
How actual performance compares with your budget or forecast
Which clients, projects, products, or services are driving the results
Whether your most important KPIs are moving in the right direction
Where something may need your attention
The exact content should reflect how your business operates and what you’re trying to achieve.
An agency might need to understand profitability by client or project. A hospitality business may need visibility over labour and food costs. An ecommerce company might be more focused on product margins, stock, and the relationship between advertising spend and profitable growth.
A generic pack containing every number available can leave you with more information but no greater understanding. Useful reporting focuses attention on the measures that affect your goals and the decisions in front of you.
It also needs to be based on clean, accurate and properly reconciled records. If the underlying data is unreliable, the conclusions you draw from it may be unreliable too.
Not every business needs to meet with its accountant each month. Some owners can review their monthly information internally and reserve a deeper conversation for each quarter. Others will benefit from talking it through more frequently.
The important thing is that the information arrives while it’s still current enough to act on.
What Should Happen in a Quarterly Review With Your Accountant?
A performance report gives you the evidence. A quarterly review helps you interpret it.
The most useful conversations spend less time reciting figures and more time exploring what sits behind them.
Your quarterly review should help you answer questions such as:
Where are we compared with the plan?
What’s changed over the past three months?
What’s driving that change?
Which parts of the business are performing particularly well?
What deserves more attention?
Are our original assumptions still realistic?
What important decisions are approaching?
Where should we focus over the next 90 days?
This is where your accountant’s understanding of your business becomes particularly valuable.
A margin change means very little without context. Your accountant needs to understand how you make money, how the team operates, what has changed, and what you’re trying to achieve before they can help you interpret it properly.
A quarterly review should also lead somewhere. By the end of the conversation, you should know what’s been decided, which actions need to be taken, who owns them, and when they will be reviewed again. Otherwise, the meeting may have been informative without making any meaningful difference to the business.
Where Do Your Year-end Accounts Fit?
Your year-end accounts remain an essential part of the rhythm. They help ensure your statutory responsibilities are met, confirm the company’s annual financial position, and support the preparation of its tax return.
They can also provide a useful opportunity to reflect on the full year. What changed? Which decisions produced the expected result? Where did the business perform differently from the plan? What should those lessons mean for the year ahead?
The difference is that year-end should not be the first time you ask those questions.
When you’ve been reviewing performance throughout the year, your annual accounts become part of an ongoing picture rather than a set of figures you’re seeing long after the events they describe.
When Should You Speak to Your Accountant Between Reviews?
A regular rhythm gives your accounting relationship structure, but it shouldn’t prevent you from having conversations when they’re needed.
Some decisions are too important to leave until the next scheduled meeting.
You may want to speak to your accountant before:
Hiring or restructuring your team
Making a significant investment
Changing your pricing
Taking on new premises
Applying for funding
Launching a new service or revenue stream
Making a substantial dividend or remuneration decision
Entering a period of cash pressure
Buying, selling or restructuring a business
The timing matters. If you are considering another hire, for example, your accountant can help you understand the full cost, test different start dates, and see what the decision could mean for cash over the months ahead.
Once the offer has been made and the person has started, the conversation becomes very different.
Your accountant can contribute far more before a significant decision is made than after its financial consequences have already begun to play out.
Do You Need Monthly or Quarterly Meetings?
The right frequency depends on the pace, complexity, and current priorities of your business.
Monthly meetings may be more valuable when:
The business is growing or changing quickly
Cash is tight or unpredictable
Margins need close attention
You have several teams, locations, or revenue streams
You’re hiring, investing, or raising funding
You’re working through a challenging period
Your board or leadership team needs regular accountability
Quarterly meetings may provide enough support when:
The business is relatively stable
Your financial systems and records are in good order
Monthly reports are reviewed internally
Fewer significant decisions are being made
You can access advice between formal reviews when needed
Meeting more often is not automatically better. The goal is to create a rhythm that suits the decisions you need to make.
That rhythm may also change. The support that worked when you were building the foundations may no longer be enough once you have a larger team, more complex operations or bigger ambitions.
Your accounting relationship should be able to grow with you.
Has Your Accounting Support Kept Pace With Your Business?
If you’re unsure whether your current service still fits, ask yourself:
Do I receive useful financial information while there’s still time to act?
Do I understand what’s driving changes in performance?
Do our review meetings result in clear decisions and actions?
Does my accountant understand our business model and goals?
Can I speak to them before making a significant decision?
You don’t need to receive every possible report or spend hours in meetings. You need information and conversations that help you understand where the business stands, what requires attention, and what your options look like.
If that’s not currently happening, these questions can help you get more value from your accountant.
What Better Accounting Support Looks Like in Practice
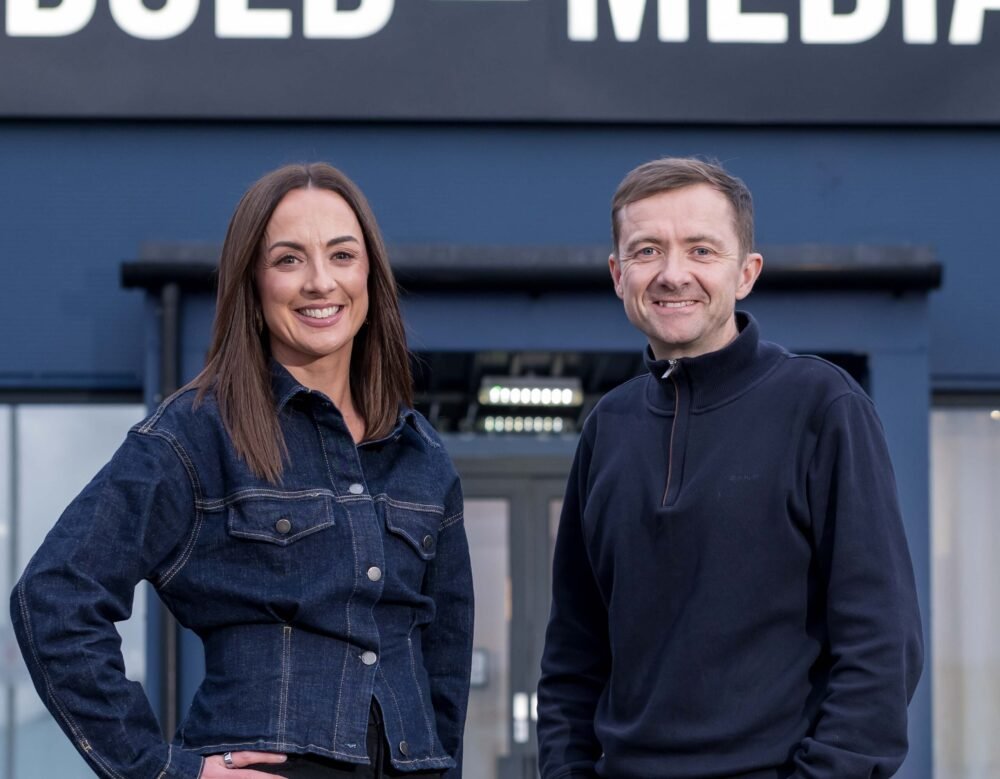
When Bold St Media came to Ashton McGill, the agency was growing, but its financial systems weren’t keeping pace.
By introducing tailored Xero reporting, meaningful KPIs, and clearer performance information, we helped the team move beyond limited year-end reporting and build a more proactive way of managing the business.
They gained a better understanding of where the agency was performing well, where changes were needed, and how their financial information could support more confident decisions.
You can read more examples in the real ROI of great accounting.
That is the standard useful accounting support should meet. The value is not simply in producing a report. It’s in what that report helps you understand, decide and do next.
Build an Accounting Rhythm Around the Business You’re Becoming
There’s no perfect meeting schedule for every company. But if you’re running a growing business, receiving a set of accounts once a year is unlikely to give you the current information needed to manage performance and make confident decisions.
Monthly visibility helps you see what’s happening.
Quarterly conversations help you understand why it’s happening and decide what to do next.
Annual accounts make sure the essential work is completed properly.
And access to advice means you can consider the financial reality of an important decision before you commit.
That’s what a better accounting experience should give you: reliable foundations, a clearer understanding of your business, and the support to keep moving towards where you want to go.
If this has made you question whether your current accounting support still fits the business you’re building, our free switching checklist will help you assess the relationship and understand what to ask next.
Frequently Asked Questions
-
It depends on the size, complexity and pace of the business. For a growing business, quarterly reviews supported by up-to-date monthly information provide a useful starting point. Monthly meetings may be more appropriate during rapid growth, cash pressure or significant change.
-
Not every business needs the same level of reporting. Monthly management accounts or performance reports become particularly valuable when you need to monitor cash, margins, budgets, KPIs or different areas of the business closely.
-
A quarterly review should cover performance against the plan, significant changes, emerging risks or opportunities and the decisions approaching over the next few months. It should end with clear priorities and agreed actions.
-
Year-end accounts are formal annual records produced to support statutory and tax requirements. Management accounts are prepared during the year for internal use, helping owners understand current performance and make decisions.
-
Speak to your accountant before making a decision that could materially affect the finances of the business. That could include hiring, investing, changing prices, seeking funding, taking on premises or responding to cash pressure.